Does home insurance cover a leaking roof in Australia?
Home insurance covers roof leaks from sudden events like storms, and refuses leaks from wear and tear. A Melbourne roofer who writes reports for claims explains how assessors decide, and how to document yours.


Short answer: usually yes if the leak came from a sudden, identifiable event like a storm, hail or a falling branch, and usually no if it developed gradually through wear and tear or lack of maintenance. Nearly every claim turns on that one distinction. Document the damage the day it happens, get a roofer's report, and do not confuse "old roof" with "uninsurable roof": an old but maintained roof damaged by a storm is still a valid claim.
I am a roofer, not an insurance broker, but I end up inside this question constantly, because the report the assessor reads about your roof is often written by someone like me. I have written reports that got claims paid and I have inspected roofs where I had to tell the owner the insurer would knock it back, and why. Here is how it actually works, in plain language. Policies differ, so treat this as general information and check your own PDS.
The rule that decides your claim: sudden vs gradual
Australian home policies insure events, not deterioration. A storm that lifts tiles on Tuesday night is an event: there is a date, a cause and matching damage. Pointing that has been cracking for eight years until water finally found the ceiling is deterioration: no event, just time. The first is what insurance exists for. The second is what maintenance exists for, and insurers exclude it explicitly under wear and tear, gradual damage and lack of maintenance clauses.
Where it gets contested is the middle ground: a storm exposes a weakness that was already there. Say wind lifts ridge caps that were held by perished mortar. Was that storm damage or pre-existing deterioration? In practice, assessors look at whether the damage pattern matches the weather event, and whether the roof was in reasonable condition beforehand. Which is exactly why the state of your maintenance matters so much.
Storms are where most sudden roof damage comes from, and they're expensive. The biggest insured events to hit Victoria since 2020 are below; the Valentine's Day storms of February 2024 alone brought about 27,800 claims worth $237 million (Insurance Council of Australia).
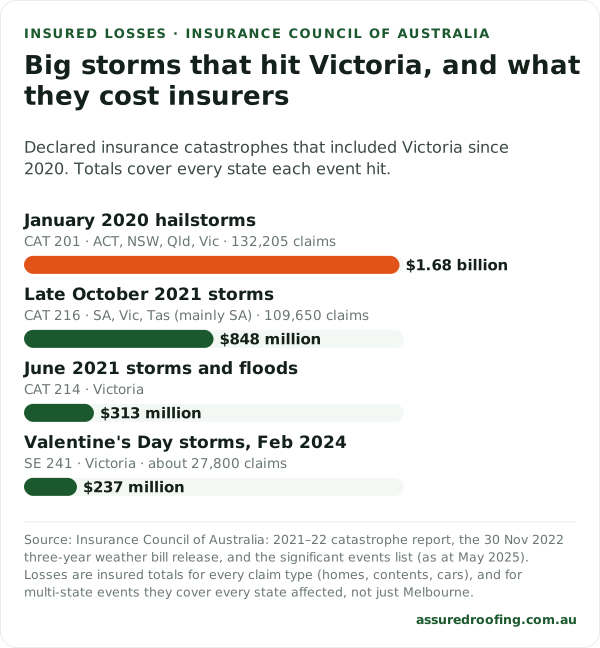
Declared insurance catastrophes that included Victoria since 2020, by insured loss (Insurance Council of Australia). Totals cover every state each event hit.
If hail was the cause, here's what hail does to a roof and what to do next.
When a leaking roof usually IS covered
Storm damage: wind-lifted or dislodged tiles and ridge caps, damage matching a recorded weather event in your area
Hail: cracked tiles, dented metal roofing and flashings
Impact: a falling tree or branch, or debris blown onto the roof
Resulting damage inside: ceilings, insulation, carpets and contents damaged by water from an insured event are generally covered as part of the claim
When it usually is NOT covered
Gradual leaks: water that has clearly been getting in over months or years (staining with history, rot, long-term rust trails)
Wear and tear: perished pointing, corroded valleys and rusted-out gutters that simply reached the end of their life
Lack of maintenance: blocked gutters that overflowed, moss dams, or damage a reasonable inspection would have caught
Faulty workmanship: leaks caused by a bad repair or installation (that is a warranty issue with the tradesperson, not an insurance event)
Scenario | Likely outcome |
|---|---|
Storm last night, tiles visibly displaced, ceiling wet today | Covered in most policies |
Hail event, cracked tiles across one face | Covered |
Branch through the roof in wind | Covered, including make-safe |
Ceiling stain that has been growing for months | Likely refused as gradual damage |
Pointing perished over 15 years, caps loose, no storm | Likely refused as wear and tear |
Gutters blocked with leaves overflowed into eaves | Likely refused as lack of maintenance |
What the assessor is actually looking for
When an assessor (or the roofer reporting to them) gets on your roof after a claim, they are reading the roof like a timeline. Fresh breaks in tiles show clean, sharp faces; old cracks are weathered grey inside with dirt tracks through them. New rust scratches look different from ten-year rust blooms. Displaced caps with fresh mortar faces say storm; caps sitting loose on powdered, moss-grown mortar say time. They will also check whether the damage direction matches the recorded wind, and whether the "storm damage" is suspiciously confined to the one spot that was already failing.
I say this not to make it sound adversarial but so you understand: the roof tells the truth. If your damage is genuinely from the storm, the evidence is on your side, and your job is simply to preserve and present it well.
Two claims, two outcomes
Two roofs I inspected in the same month tell the whole story. The first, a concrete tile roof in Melbourne's east: a front had come through, and a run of ridge caps had lifted and slid. The mortar faces were freshly broken, tiles below were newly chipped where caps had struck them, and the damage lined up with the recorded wind direction. My report said exactly that, with photos. Claim paid, including the water-stained ceiling inside.
The second: a ceiling leak "after the storm" where the actual entry was a valley iron that had been rusting for a decade, with staining on the roof timbers that had clearly built up over many wet seasons. There was no storm damage on that roof at all. The insurer refused it as gradual damage and, honestly, the refusal was fair under the policy. The owner ended up paying for the valley replacement themselves, which years of cheap annual inspections would have flagged long before the ceiling let go.
How to give your claim the best chance
Photograph and video everything on day one: the ceiling, the water, the sky if the storm is still visible, and the roof from the ground. Date-stamped phone photos are fine.
Check the Bureau of Meteorology records for your suburb and date, and note them. A recorded severe weather event near your address anchors the whole claim.
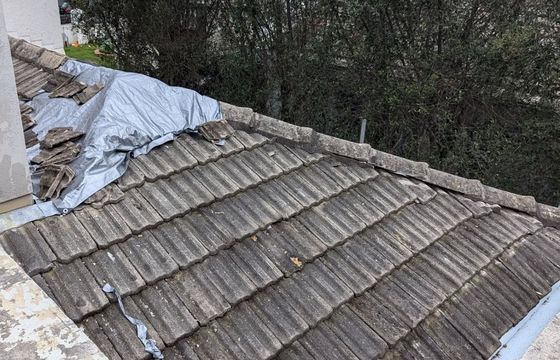
Make safe, but keep evidence: do not repair, re-point or replace anything before the insurer has seen it or approved it. Keep any broken tiles and displaced caps rather than binning them.
Contact your insurer promptly. Most policies require notification within a reasonable time, and delay reads badly.
Keep receipts for any emergency make-safe work like tarps; these are usually claimable.
Get an independent roofer's report with photos, describing the cause and distinguishing fresh damage from wear. This is the single most useful document you can add.
Keep your maintenance history: gutter cleaning receipts, past repair invoices, inspection reports. They rebut the lack-of-maintenance argument before it starts.
The Insurance Council adds three things: photograph before you clean up, keep samples and anything repairable, and get your insurer's permission in writing before any repairs, including emergency ones. Under the insurance Code of Practice, your insurer should respond within 10 business days and decide within 4 months, with some exceptions (Moneysmart).
If your claim is knocked back
You do not have to accept the first answer. Ask for the refusal in writing with the specific policy clause relied on, then use the insurer's internal dispute process. If that fails and you still believe the decision is wrong, the Australian Financial Complaints Authority handles insurance disputes free of charge. An independent roofer's report addressing the insurer's stated reason carries real weight at both stages. For plain-language guidance on policies and claims generally, Moneysmart's home insurance guide is the best neutral resource going.
A declined claim must be in writing with reasons, and you can ask for the reports it relied on, which the insurer should supply within 10 business days (Moneysmart). If you still disagree after the insurer's own complaints process, the Australian Financial Complaints Authority is free on 1800 931 678.
The maintenance duty nobody reads
Every policy contains some version of "you must keep the home in good repair". In practice that means: clean gutters, no long-standing known leaks, and a roof that gets looked at occasionally. It does not require a new roof. An older roof that has been reasonably maintained is still fully insurable for storm damage. If your roof has not been looked at in years, a professional inspection and any needed repairs does two jobs at once: it protects the house, and it builds the paper trail that protects your next claim. If a leak has already appeared, our guide on how to fix a leaking roof covers what to do in the first hour.
The Insurance Council says it plainly: a lack of maintenance can reduce a payout or lead to a claim being denied.
Sources and methodology
Every figure in this guide comes from a published source or from our own work. Here is where each one came from and how we used it.
Where the numbers come from
Insurance Council of Australia, after a severe storm: photograph first, tell your insurer early, written permission before repairs. Checked 20 September 2026.
Insurance Council of Australia, FAQs after a disaster: lack of maintenance can reduce a payout or lead to a claim being denied. Checked 20 September 2026.
Moneysmart (ASIC): claim timeframes under the insurance Code of Practice and declined claims. Checked 20 September 2026.
Australian Financial Complaints Authority: free complaints service, 1800 931 678. Checked 20 September 2026.
Insurance Council of Australia, catastrophe reports and significant events: insured losses for the events in the chart. Checked 20 September 2026.
Insurance Council of Australia, three-year weather bill (30 November 2022): January 2020 hail: $1.68 billion from 132,205 claims. Checked 20 September 2026.
Australian Financial Complaints Authority: linked in this guide.
Moneysmart's home insurance guide: linked in this guide.
How we worked them out
Timeframes and rights are as described by Moneysmart and the Insurance Council; your policy wording decides your claim. Insured losses are the Insurance Council's figures and cover every state an event hit. The roof advice and what we see on jobs come from our own work on Melbourne roofs.
Good to know every policy is different. This is general information from a roofer, not insurance or legal advice.
Checked by Ryan Airey on 20 September 2026. Next review: March 2027. How we research, write and check our guides: editorial policy.
Frequently asked questions
Is a roof leak in heavy rain covered by insurance?
Heavy rain alone is not the test. If the rain was part of a storm event that damaged the roof, yes, usually. If heavy rain simply found its way through worn pointing or blocked gutters, that is generally excluded as wear and tear or lack of maintenance.
Does home insurance cover roof restoration or replacement?
Insurance repairs insured damage; it does not fund maintenance or betterment. If a storm damages part of the roof, the insurer covers that repair. It will not pay to restore or replace a roof that has simply worn out.
Will insurance cover a leak in an old roof?
Age alone does not void cover. An older roof in reasonable, maintained condition that gets storm damaged is still a valid claim. What hurts claims is deterioration and neglect, not the year the roof was built.
Do I pay the excess on a roof leak claim?
Yes, your policy excess applies to roof and water damage claims like any other. For small repairs it is worth comparing the excess against the repair cost before claiming, since a modest repair can cost less than the excess plus any premium impact.
Are temporary repairs and tarps claimable?
Reasonable emergency make-safe costs, like a professionally fitted tarp after storm damage, are usually claimable and often actively encouraged by insurers to limit further damage. Keep every receipt and photograph the work.
How long do I have to lodge a roof damage claim?
Notify your insurer as soon as reasonably possible. Policies expect prompt notification, and a months-old claim for storm damage invites the argument that the damage was gradual. Day-one photos and a prompt lodgement remove that argument.